Pillar 1 ... Free enterprise.
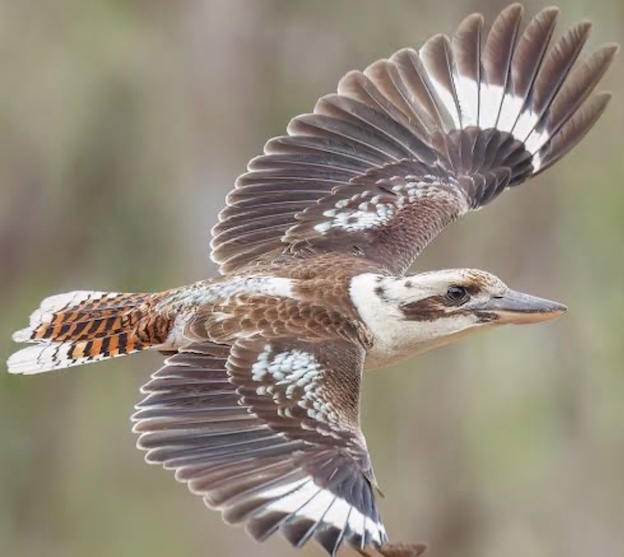
The kookaburra is free to fly where it wants with minimal interference. Aussies should also be free to live their lives with minimal interference from the government. We Aussies need an efficient government that does not overspend (nor underspend) on unnecessay bureaucratic functions which have already been performed elsewhere. If we won a majority of seats in both houses of parliament, we would keep existing staff but halt new hires.Being public servants, such office staff will not lose their jobs but will be subject to an efficient rotation system so that Australian governmental functions can be more efficiently performed.
................................................................
For everyday Aussies to run their lives freely (with minimal interference), governments must be run efficiently. Not harshly but efficiently. Public spending must not crowd out private investments. Hopefully, that way, we can grow the economic pie and not fall behind in the productivity and prosperity stakes.
...............................................................
To the productivity end, if we won a majority in both houses of Parliament, the mandatory 30% tax on capital gains in shares will be wound down to 15% (to equalise contributions within super and outside super). Aussies need to have equal choices with respect to where they invest their hard earned money. This measure will encourage investment in businesses either way (within super or outside of it). The money generated by the tax will be used to reduce the national public debt. Once done, this taxing of shares will return to the pre budget taxation system whereby capital gains in shares will add to personal taxable income and then taxed according to the progressive tax brackets applicable at the time. There will be no extra mandatory 30% tax. Of course, if an Aussie were on a marginal tax rate of 30% in August 2026, (due to a taxable income between $45k and $135k), then 30% tax will be applied. It will be 30% because that person has a taxable income rate of 30% and not because of the mandatory 30% tax (which, as mentioned above, will be phased out once the national debt has been cleared.) Note that our government will be flexible and if the government debt were to increase (due to the social needs of the population), then we may have to increase taxes. That revenue will be used to reduce the debt. A society should not be living beyond its means and our government will abide by that philosophy. We plan to keep government spending at or below 3% of gdp to help with this goal of earning more than we spend.
The compulsory super system we have here in Australia has been a great boon to our country. It is not governmental money and we plan to keep our hands off of it. We plan to continue to tax those with balances over $3 million and $10 million For balances in accumulation mode, the tax on entering super will continue to be 15%, as will the earnings on the accumulation balance. This number (15%) may have to be increased in the future if need be (to match the marginal tax tax rate outside of super) but when it moves to the income phase, that balance will cease to be taxed (as long as super is compulsory). If super became optional in the future, then earnings will be taxed at the member's marginal tax rate. Transfer balance caps will continue to be indexed to inflation. The non taxing of super left to spouses and dependents will continue, as will the 17% tax on untaxed super that is left to non dependent adult offspring.
Many btrusts have had to incur state stamp duty (again ...) when they moved from a trust structure to a company structure (due to the 2026 budget restrictions). That was not fair as these businesses had set up those trusts in good faith and had not expected the government of the day to change the rules mid stream.Asking them to do an about turn again, would also not be fair.Consequently, we would be looking into ways to changing company law in such a way that these businesses would be helped. This is a complicated legal minefield and no promises will be made. We will look into
The new 2026 cgt and negative gearing provisions on existing residental property will, however, remain. Property is for living in and we should not spend too much speculative money building wealth in bricks and mortar when that same money can be used to increase productivity in businesses (via shares). Nor should we be spending tax payers' money on tax rebates that only help one group of society and not others. That this had already happened is very regrettable but hopefully, having a level playing field from hereon in will prove to be fairer to all Australians.